
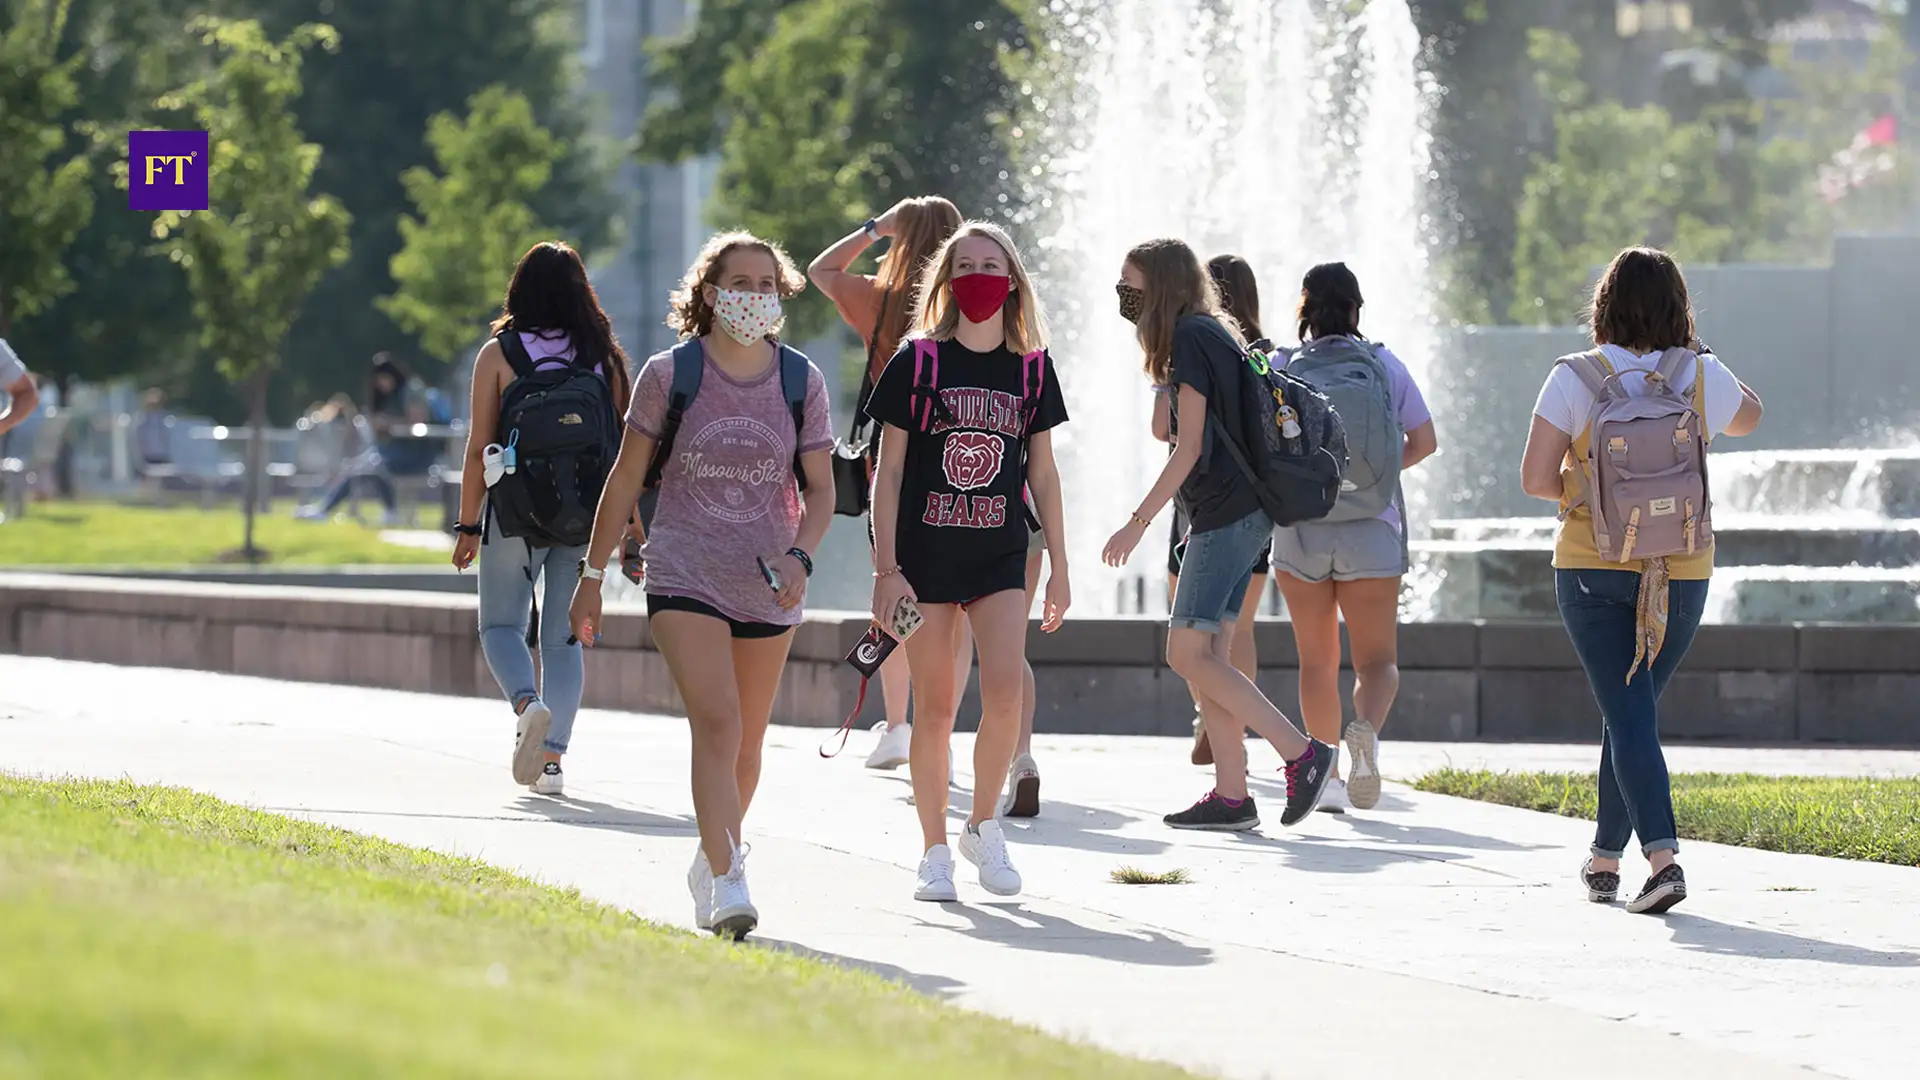 Photo by FT
Photo credit: Pexels
- A yearlong personal-finance course could give students more time to study budgeting, saving, investing, credit, debt, taxes and college expenses.
- More foreign-language instruction could move into K-8, with high school courses reserved for advanced language study.
- Colleges, trade schools and state education departments could raise financial-literacy standards and expand the pool of qualified teachers.
NEW YORK, Oct. 5, 2026 — American education faces questions about school funding, curriculum, and school choice. Financial literacy should be part of that discussion. Students will earn, spend, save, and borrow money throughout their adult lives, yet personal-finance requirements remain limited in many states. Missouri, for example, requires students to complete one-half credit of personal finance to graduate from high school. One semester provides limited time to teach income, expenses, credit, debt, saving, investing, and taxes.
High school is also when many students begin handling money themselves. Teenagers may get their first jobs and paychecks, open bank accounts, obtain driver's licenses and begin paying for transportation, insurance and other expenses. They also begin making decisions about college costs and student loans. High schools require mathematics, science, English and history because students need that knowledge for college, careers and adult life. Financial literacy deserves comparable classroom time because students will use those skills throughout adulthood.
Foreign Language in K-8
Foreign-language education provides academic and career benefits. Spanish, French, German, and other languages can help students communicate across countries and industries. Some American colleges and universities require or recommend foreign-language study, while highly selective schools may expect multiple years of coursework. Foreign-language education has value, but the amount of high school classroom time devoted to it deserves reconsideration when personal finance receives only limited instruction.
Many K-8 students receive some foreign-language instruction, sometimes for one or two days a week or for only part of the school year. Students can then take yearlong language courses in high school to meet college expectations. More foreign-language instruction could be provided in elementary and middle school, giving students several years to build language skills. Students who want advanced study could continue with Spanish, French, German or another language in high school. Students who become proficient could use those skills in college and careers involving international customers, clients or colleagues.
Teenagers and Money
Students face financial decisions before they graduate. A first paycheck requires an understanding of income and payroll deductions. A driver’s license can lead to expenses for a vehicle, insurance and fuel. A bank account requires knowledge of deposits, withdrawals, balances and fees. Credit cards introduce interest charges and debt. College decisions can involve tuition, financial aid and student loans. Saving and investing introduce additional financial choices that can affect a person’s finances for years. These subjects require more classroom time than a brief introduction during one semester.
Other graduation requirements show why financial literacy needs more time. A high school that required only one semester of mathematics, science, or history would raise questions about whether students had received enough instruction in those subjects. Missouri requires one-half credit of personal finance, even though students can face financial decisions involving thousands of dollars soon after graduation. A yearlong personal-finance course could cover budgeting, saving, investing, credit, debt, taxes and college expenses. Teachers could use examples involving part-time jobs, bank accounts, vehicle costs and student loans to connect financial concepts with decisions teenagers already face.

Photo credit: Pexels
Colleges Can Raise Standards
Colleges and universities can influence what financial knowledge students acquire before applying. Higher education institutions already evaluate applicants based on coursework in mathematics, science, English, and other subjects. Financial literacy could become another academic requirement for admission. Trade schools and other postsecondary programs could adopt the same requirement because their students will also earn income, manage expenses, and make decisions about credit and debt. Colleges could also recognize foreign-language study completed during K-8 and reserve high school language courses for students seeking advanced proficiency.
State departments of education can expand the pool of financial-literacy teachers by considering relevant professional and personal financial experience when evaluating educators for these positions. Teachers with experience managing budgets, credit, investments, taxes, or other financial matters can draw on that experience in the classroom. Foreign-language education should remain available, but high schools should devote more classroom time to personal finance when students are beginning to earn and spend money. Students should graduate knowing how to read a paycheck, manage a budget, understand borrowing costs, evaluate debt, and make informed decisions about saving and investing.
A semester of personal finance is a thin foundation for a lifetime of financial decisions.
Related Topics
How Smart Devices Help You Understand Money and Reach Your Financial Goals
Smart devices give you a clear picture of your spending, energy use, and health costs, making it easier to stay on top of your money and build savings.
By
Money and Mindset Go Hand in Hand
Financial success isn’t just about the money you earn. It’s about the way you think, plan, and act with it every day.
By
Why Half of Americans Struggle with Everyday Money
Many adults lack the basic skills needed to budget, save, and plan for the future, leaving them unprepared for life’s financial challenges.
By
Money & Mindset: 6 Steps to Create a Positive Mindset
A positive mindset does not eliminate challenges. It equips you to respond to them with clarity and purpose.
By