
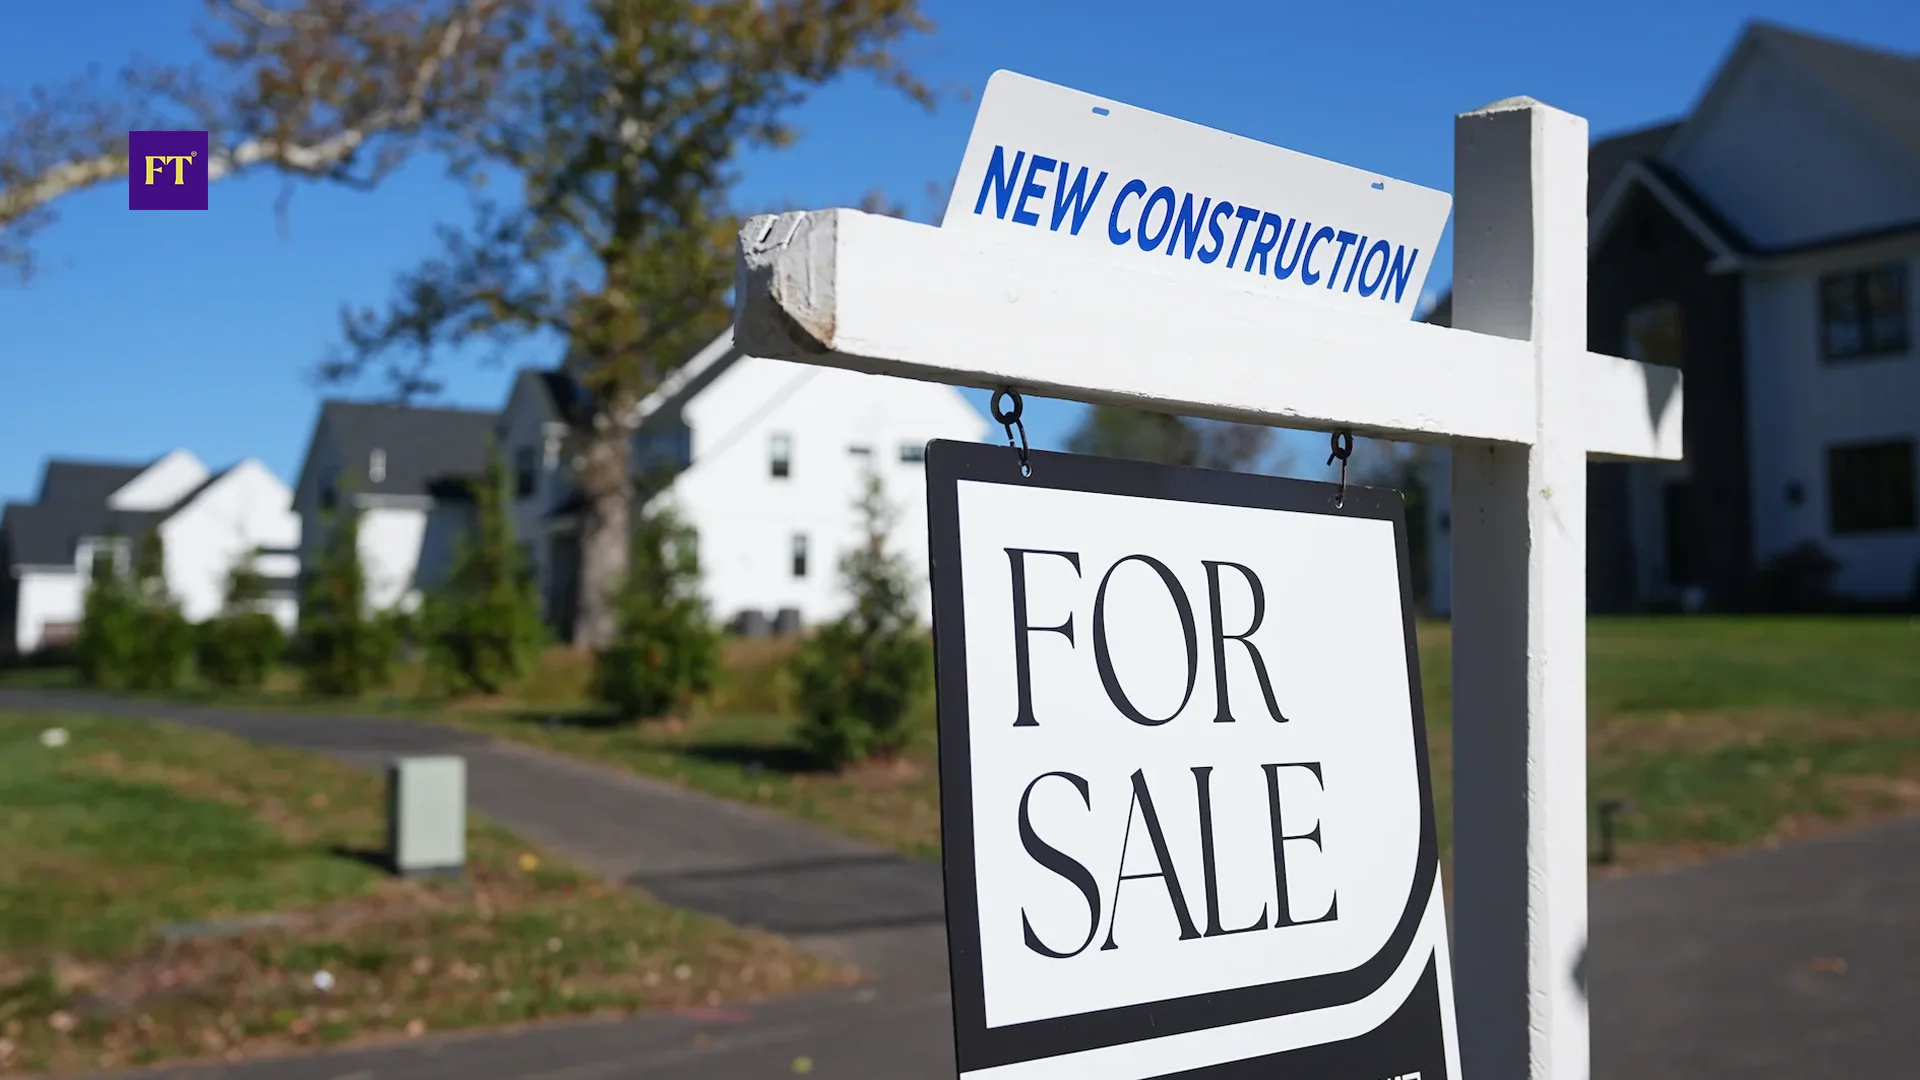
 Photo by FT
Image credit: Pexels
- The average 30-year purchase mortgage rate fell to 7.326%, while home purchase mortgage applications remained 18% below year-ago levels.
- Inflation, oil prices, and the Iran war influence Treasury yields and mortgage rates as markets anticipate the Federal Reserve will hold its benchmark rate unchanged.
- Experts expect 30-year mortgage rates to remain above 6% for the next several years, limiting affordability and discouraging some homeowners from selling.
WASHINGTON, Oct. 27, 2026 — Mortgage rates remain a major hurdle for U.S. homebuyers as inflation, oil prices and geopolitical tensions affect bond yields. Although rates have fallen since early October, home loans remain expensive, and mortgage applications for home purchases are 18% lower than a year ago.
The average rate on a 30-year purchase mortgage fell to 7.326% on Tuesday, down from 7.349% the previous day, according to Zillow data. The average 30-year refinance rate stood at 7.429%, while the 15-year refinance rate reached 6.483%. Since early October, the 30-year purchase rate has declined by 30 basis points, or 0.30 percentage points.
Inflation and Mortgage Rates
September’s consumer price index report showed consumer prices climbing slightly faster than economists had forecast. Higher-than-expected inflation can push mortgage rates upward as investors demand greater returns on bonds to offset the loss of purchasing power. Recent movements in the bond market have partly offset that effect.
Treasury yields initially climbed after the inflation report but later declined as investors sold stocks and moved money into bonds. Mortgage rates generally move in the same direction as yields on 10-year U.S. Treasury notes, making bond trading an important indicator of mortgage borrowing costs.
Inflation expectations and Federal Reserve policy both influence Treasury yields. When investors expect consumer prices to climb, they often demand higher bond yields to compensate for the erosion of purchasing power. Expectations for the Fed's benchmark interest rate also affect bond prices and yields, which in turn influence mortgage rates.
High Rates Slow Home Sales
High mortgage rates limit homebuyer demand by raising monthly payments and making homes more expensive. Homeowners with lower-rate mortgages also have less incentive to sell and take out a new loan at today's higher rates.
The Mortgage Bankers Association, an industry trade group, reported that its unadjusted purchase index was 18% lower than a year ago. The index tracks applications for mortgages used to buy homes and serves as an indicator of homebuyer demand.
Lower mortgage rates could improve affordability, but the outlook depends on inflation data, Treasury yields and expectations for Federal Reserve policy. Until borrowing costs fall, some buyers may delay purchases, while homeowners with lower-rate mortgages may remain reluctant to sell.
Fed Decision and Oil Prices
The Federal Reserve’s October meeting is scheduled to conclude Wednesday, Oct. 28. Markets are pricing in an approximately 90% probability that policymakers will leave the benchmark interest rate unchanged, according to the CME Group’s FedWatch tool, which tracks market expectations through federal funds futures prices.
Melissa Cohn, regional vice president of William Raveis Mortgage, has warned that surging oil prices could add to inflation and affect Treasury yields even if the Fed leaves its benchmark rate unchanged. “The 10-year Treasury is below five percent for the first time in over a month, but at some point, the high rising oil prices are going to bite us,” Cohn says.
Higher oil prices can raise manufacturing and transportation costs. If those expenses feed into consumer prices, investors may expect inflation to remain elevated and demand higher returns on Treasury securities. That could push mortgage rates upward.

Image credit: Pexels
Iran War Influences Treasury Yields
Mortgage rates have climbed since the U.S. war in Iran began in late February. Signs of military escalation have tended to push 10-year Treasury yields and mortgage rates higher, while developments suggesting a possible end to the conflict have coincided with declines in both. Treasury yields fell after President Donald Trump announced last week that the United States would not strike Iran before the Nov. 3 midterm elections.
The decline reflected changes in investor expectations about the conflict and its economic consequences. Research from the Federal Reserve Bank of Dallas examined several possible scenarios for the war's effect on inflation. Depending on the scenario, the paper estimated that U.S. headline inflation in the fourth quarter of 2026 could be 0.2 to 1.8 percentage points higher than it would otherwise have been.
Higher oil prices can raise production and transportation costs across multiple industries, adding to consumer prices. Further escalation could send oil prices higher and prompt investors to demand greater returns on bonds to offset anticipated inflation. Signs of de-escalation could ease those concerns and help Treasury yields and mortgage rates fall.
Mortgage Rates Likely to Stay Above 6%
Most experts expect mortgage rates to remain elevated over the next several years, with the average rate on a 30-year fixed-rate loan staying above 6%, according to forecasts cited by U.S. News.
An unexpected change in the U.S. economy could send rates tumbling, but a return to levels below 3% or even 4% appears unlikely in the foreseeable future. Homebuyers may therefore face borrowing costs well above those available during the period of historically low rates.
The immediate outlook depends on the Federal Reserve's decision, upcoming inflation data, Treasury yields, and developments in the Iran war. Unless borrowing costs fall substantially, high monthly payments are likely to limit buyer demand, while homeowners with lower-rate mortgages may remain reluctant to sell.
The Mortgage Bankers Association, an industry trade group, reported that its unadjusted purchase index was 18% lower than a year ago. The index tracks applications for mortgages used to buy homes and serves as an indicator of homebuyer demand.
Related Topics
How Real Estate Investment Trusts Work and What Investors Should Know
A REIT must be organized as a corporation, trust or association and be managed by a board of directors or trustees.
By